
You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.
inflation
- Thread starter sculptor
- Start date


Because inflation is better than deflation. The Fed wants to avoid a deflationary spiral at all costs. The 2% inflation rate provides a buffer against deflation. We all gain. We all benefit from that policy.Why does the federal reserve bank want inflation?
If the fed achieves 2% inflation, the currency loses 1.96% of it's value annually.
Who gains?
Is inflation necessary in support of our economy?
It is necessary for us to be able to pay off our debt.Why does the federal reserve bank want inflation?
If the fed achieves 2% inflation, the currency loses 1.96% of it's value annually.
Who gains?
Is inflation necessary in support of our economy?
The answer is no. It's only necessary to service the debt.It is necessary for us to be able to pay off our debt.
It's not necessary for either.
Debt servicing and repayment comes from cashflow, which does not need inflation to operate.
But what billvon is alluding to, I think, is that it helps reduce the future value of existing debt capital.
As to why the government / central bank might want a certain level of inflation, it is because there is a thought to be a relationship between inflation and unemployment.
The lower the unemployment, the higher the inflation, and vice versa.
You can't eliminate both, it seems, so you reach a compromise - such as 2%.
Governments in the past had tried to set other financial targets as their underlying policy, but setting an inflation target has seemed to be the most effective, at least in recent times, for helping to keep the economy in reasonable control.
Debt servicing and repayment comes from cashflow, which does not need inflation to operate.
But what billvon is alluding to, I think, is that it helps reduce the future value of existing debt capital.
As to why the government / central bank might want a certain level of inflation, it is because there is a thought to be a relationship between inflation and unemployment.
The lower the unemployment, the higher the inflation, and vice versa.
You can't eliminate both, it seems, so you reach a compromise - such as 2%.
Governments in the past had tried to set other financial targets as their underlying policy, but setting an inflation target has seemed to be the most effective, at least in recent times, for helping to keep the economy in reasonable control.
Exactly. And with Trump in office, inflation will be the only thing that keeps our (effective) deficit from rising at a crippling rate.It's not necessary for either.
Debt servicing and repayment comes from cashflow, which does not need inflation to operate.
But what billvon is alluding to, I think, is that it helps reduce the future value of existing debt capital.
And where does that come from? It is certainly necessary to service the debt, else you default.It's not necessary for either.
Debt servicing and repayment comes from cashflow, which does not need inflation to operate.
Yes, the money needed to service the debt comes from cash flow, but it has nothing to do with inflation.
But what billvon is alluding to, I think, is that it helps reduce the future value of existing debt capital.
Inflation does devalue existing debt. Higher interest rates devalue existing debt too.
As to why the government / central bank might want a certain level of inflation, it is because there is a thought to be a relationship between inflation and unemployment.
The lower the unemployment, the higher the inflation, and vice versa.
You can't eliminate both, it seems, so you reach a compromise - such as 2%.
Governments in the past had tried to set other financial targets as their underlying policy, but setting an inflation target has seemed to be the most effective, at least in recent times, for helping to keep the economy in reasonable control.
Which basically amounts to a barrier to deflation.
How do you figure? How does that make sense? The thing which will keep inflation under control is Trump's incompetence.Exactly. And with Trump in office, inflation will be the only thing that keeps our (effective) deficit from rising at a crippling rate.
Trump has promised a massive fiscal stimulus, a stimulus that dwarfs anything Obama did in 2009 when it was needed. Trump's fiscal stimulus would be massively inflationary given we are at or near full employment now.
The Federal Reserve is increasing interest rates to offset any future inflation. The reason we will not see crippling inflation is because Trump cannot get his inflationary fiscal spending through a Republican controlled Congress. And even if he did, it would be offset by the Federal Reserve's monetary tightening. Ironically, we have Trump trying to gas the economy with massive fiscal stimulus while we have the Federal Reserve applying the breaks.
Last edited:
Ah - I see the confusion: when you stated "It's only necessary to service the debt" I took the "it's" to be continuing the reference to inflation.And where does that come from? It is certainly necessary to service the debt, else you default.
...
Yes, the money needed to service the debt comes from cash flow, but it has nothing to do with inflation.
I.e. it was as though you were saying "Inflation is only necessary to service the debt".
When Billvon said that "It is necessary for us to be able to pay off our debt" he was referencing inflation with "it" (i.e. "inflation is necessary for us to pay off our debt") and you seemed to be continuing that reference.
Now I see that you were not intending that.
Agreed that Inflation does devalue existing debt, but disagree that higher interest rates devalue it.Inflation does devalue existing debt. Higher interest rates devalue existing debt too.
Interest rates only affect the servicing costs of the debt, not the value of the underlying capital.
Only inflation/deflation does that.
If one does not pay the increased servicing costs then yes, your total debt will increase, but this is new debt, not the existing debt.
Furthermore, higher interest rates actually tend to work to reduce inflation.
Yes, trying to achieve inflation of 2% is indeed an effort not to have negative inflation.Which basically amounts to a barrier to deflation.
It is also an effort not to have inflation of only 1%.
Simply put, I found your "inflation is better than deflation" explanation to be rather lacking in any actual explanatory information.
Agreed that Inflation does devalue existing debt, but disagree that higher interest rates devalue it.
Interest rates only affect the servicing costs of the debt, not the value of the underlying capital.
Only inflation/deflation does that.
If one does not pay the increased servicing costs then yes, your total debt will increase, but this is new debt, not the existing debt.
I’ll explain why higher interest rates devalue debt. Consider the following example of a hypothetical bond:
Par value (Face Value): $100
Interest Rate: 10%
Term: 30 years
The present value or price of the bond is $94.27
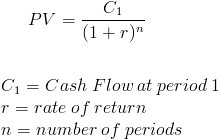
http://financeformulas.net/Present_Value.html
https://www.accountingcoach.com/present-value-of-a-single-amount/explanation/3
Now everything remains the same but interest rates rise. For this example, let’s say interest rates rise to 12%, the value of the bond declines to$80.55. There is an inverse relationship between bond prices and interest rates. When interest rates rise, bond values fall. When interest rates fall bond prices rise, it’s just a matter of math. Most people don’t understand this inverse relationship, and that’s why this is a very dangerous time for many arm chair bond investors.
Below is a more detailed explanation from Wells Fargo:
https://www.wellsfargofunds.com/ind/investing-basics-and-planning/bonds-and-interest-rates.html
Furthermore, higher interest rates actually tend to work to reduce inflation.
Yes, trying to achieve inflation of 2% is indeed an effort not to have negative inflation.
It is also an effort not to have inflation of only 1%.
Yes, higher interest rates do work to reduce inflation. But you are again conflating two very different things. Higher interest rates have the effect of reducing the money supply, and lower interest rates have the effect of expanding the money supply. That’s why higher interest rates reduce inflation. But that has nothing to do with the pricing of or valuation of debt.
Simply put, I found your "inflation is better than deflation" explanation to be rather lacking in any actual explanatory information.
You can find it lacking, but that’s the reason. The 2% inflation target is a deflation buffer. The economy doesn’t move on a dime. There are lag factors. Normally it takes time for monetary and fiscal policy to affect the economy: about 6 months, and it takes time to recognize problems in the economy. Policy makers always make policy based not on current data, but historical data. They are always looking backward at how things were and making suppositions about how things are. The economy isn’t a Ferrari 488 Spider; it’s more like a tanker. The last thing the monetary policy makers want is a deflationary spiral.
Last edited:
I find it ironic that you say I am conflating two different matters yet you try to use bonds as an example.I’ll explain why higher interest rates devalue debt. Consider the following example of a hypothetical bond:
Bonds, such as the example you offered, are a combination of principal and interest payments.
The value of such bond in your example is due to the revaluation of the value of future cash flows (i.e. interest payments) and have nothing to do with the actual time value of the principal capital, which is what is being discussed.
The actual value of the debt capital is only affected by inflation.
It doesn't matter what the interest rates are, if inflation is 2% per year then the debt capital of 100 now will be worth only 82 in 10 years time.
It is the value one attributes to the future interest payments, the servicing of that debt, that drives the value of bonds.
Your first link even assumes that for their examples "interest" is equivalent to the time value of money (aka inflation) but in reality, as you know (hopefully), the interest rate of bonds is entirely different to inflation.
If the prevailing interest rates of the market drop (proxy for how easy it is to get a certain level of return) then bonds with fixed interest (such as your example) are that much more desirable, hence their valuation increases.
Similarly if the prevailing interest rates increase then a fixed interest bond becomes less desirable, and the value decreases.
And their valuation also has little to do with and formal present value calculation but rather more simply with people's willingness to buy them (which you would hope is based on some form of valuation).
The pricing or valuation of debt such as bonds is distinct from the time value of the debt capital, which is the issue at hand.Yes, higher interest rates do work to reduce inflation. But you are again conflating two very different things. Higher interest rates have the effect of reducing the money supply, and lower interest rates have the effect of expanding the money supply. That’s why higher interest rates reduce inflation. But that has nothing to do with the pricing of or valuation of debt.
If you bring in to the discussion debt vehicles that include future cashflows based on interest rates then of course the perceived value of those future cash payments is going to affect the valuation of that debt vehicle.
But that is a red herring to what was raised by billvon.
But regardless of the valuation in the market, the actual time value of the principal, and the time value of the interest payments for that matter, is determined simply by actual inflation.
The valuation in the market, however, is determined by people's willingness to trade.
It is the same way that the value of companies on the market can trade above or below the actual net book value of their assets: the valuation in the market does not alter the actual NBV of those assets.
Yet without explaining why deflation is unwanted it lacks any actual value as an answer.You can find it lacking, but that’s the reason....
I find it ironic that you say I am conflating two different matters yet you try to use bonds as an example.
Well you are.
Bonds, such as the example you offered, are a combination of principal and interest payments.
Any investment is a series of cash flows. There is nothing magical about interest payments. Interest is just one kind of cash flow.
The discussion was about debt. Bonds are debt. You had asserted that higher interest rates do not devalue debt. I proved otherwise using a hypothetical bond as an example and a Wells Fargo article explaining in inverse relationship between the value (i.e. price) of debt/bonds and interest rates.
When interest rates go up, debt (e.g. bond prices) prices fall. Higher interest rates devalue debt, just as lower interest rates increase the value of debt.
The value of such bond in your example is due to the revaluation of the value of future cash flows (i.e. interest payments) and have nothing to do with the actual time value of the principal capital, which is what is being discussed.
I think you are confusing yourself. The values of all investments are based upon expected future cash flows. Expected cash flow is the basis for all valuations. How else to you value something if not based on future cash flows? You’ve got a little double speak going on here.
The actual value of the debt capital is only affected by inflation.
That is not true. The value of debt is affected by 5 things with inflation being one of them. The value of everything is affected by inflation. Inflation is a component of interest rates. Inflation and interest rates are not separate and apart from each other as you imply. They are deeply entwined.
http://www.investopedia.com/exam-gu...nterest-rates.asp?lgl=myfinance-layout-no-ads
It doesn't matter what the interest rates are, if inflation is 2% per year then the debt capital of 100 now will be worth only 82 in 10 years time.
Wrong, it always matters what inflation rates are, because inflation affects the value of everything, not just debt. That’s why inflation rates are so carefully monitored. Inflation rates always change. It’s the nature of the beast. The economy isn’t static. It’s always changing.
It is the value one attributes to the future interest payments, the servicing of that debt, that drives the value of bonds.
Your first link even assumes that for their examples "interest" is equivalent to the time value of money (aka inflation) but in reality, as you know (hopefully), the interest rate of bonds is entirely different to inflation.
While interest is the time value of money, it’s not something magical. There is a rational basis for interest rates which you don’t seem to be able to understand. Interest rates are not divorced from inflation rates as you have asserted. The time value of money must account for expected inflation among other factors like default risk, and it does.
If the prevailing interest rates of the market drop (proxy for how easy it is to get a certain level of return) then bonds with fixed interest (such as your example) are that much more desirable, hence their valuation increases.
Similarly if the prevailing interest rates increase then a fixed interest bond becomes less desirable, and the value decreases.
And their valuation also has little to do with and formal present value calculation but rather more simply with people's willingness to buy them (which you would hope is based on some form of valuation).
Interest is the time value of money. And as I previously wrote, expected inflation is an integral interest rate component.
How else do you value something if not by its present value? Whether you like it or not, that’s how everything is valued in the financial world, be it real estate, debt, or equity. All assets are valued based on future expected cash flows. There isn’t anything magical about debt.
The pricing or valuation of debt such as bonds is distinct from the time value of the debt capital, which is the issue at hand.
No it isn’t. You are confusing yourself with gobbledygook. Your assertion doesn’t make sense. The value of debt isn’t distinct from the time value of money (i.e. interest rates). Think about that for a moment and realize the absurdity of your assertion. Your assertion rests on your belief in the greater fool theory.
The Greater Fool Theory:
‘The greater fool theory states that the price of an object is determined not by its intrinsic value, but rather by irrational beliefs and expectations of market participants.[1]A price can be justified by a rational buyer under the belief that another party is willing to pay an even higher price.[2][3][4]In other words, one may pay a price that seems "foolishly" high because one may rationally have the expectation that the item can be resold to a "greater fool" later.’
https://en.wikipedia.org/wiki/Greater_fool_theory
If you bring in to the discussion debt vehicles that include future cashflows based on interest rates then of course the perceived value of those future cash payments is going to affect the valuation of that debt vehicle.
But that is a red herring to what was raised by billvon.
Well, that was the genesis for this discussion, but how do you exclude future expected cash flows from a discussion on debt, and how else do you value those expected cash flows if not interest rates? That’s not a red herring.
What you and Bilvon are doing is conflating monetary and fiscal policy. The two are not the same. Fiscal policy: how much revenue is raised and how much money is spent is a function of Congress. Monetary policy: the control of money supply is a function of the Federal Reserve, not the POTUS. That too isn’t a red herring. It’s a fact.
But regardless of the valuation in the market, the actual time value of the principal, and the time value of the interest payments for that matter, is determined simply by actual inflation.
The valuation in the market, however, is determined by people's willingness to trade.
It is the same way that the value of companies on the market can trade above or below the actual net book value of their assets: the valuation in the market does not alter the actual NBV of those assets.
Yet without explaining why deflation is unwanted it lacks any actual value as an answer.
This really isn’t that difficult. When interests rates go up for whatever reason, be it inflation or some other demand factor, the value of debt decreases.
Your argument boils down to this; you are saying a debt buyer would rather purchase debt yielding 8% when the prevailing market rate is 10%? Good luck with that. I don’t know of any debt investor who would buy debt yielding 8% when they could get 10% for the same risk. Your argument boils down to the greater fool theory of investing.
Markets are aggregates, and they reflect the aggregate prevailing wisdom of the market at any point in time, and that wisdom is based on expected cash flows. That’s the bottom line which is eluding you.
Last edited:
I really am not.Well you are.
Indeed - but we're talking about debt as in the principal.Any investment is a series of cash flows. There is nothing magical about interest payments. Interest is just one kind of cash flow.
Not investments.
Not cash flow.
Not anything else.
You have simply confused the matter by introducing bonds et al.
Principal plus future cash flows.The discussion was about debt. Bonds are debt.
They do not devalue the principal.You had asserted that higher interest rates do not devalue debt.
That is what was asserted, as that is what was being discussed.
No, you proved that the value of future cash flows changes with the interest rate.I proved otherwise using a hypothetical bond as an example and a Wells Fargo article explaining in inverse relationship between the value (i.e. price) of debt/bonds and interest rates.
That is not disputed.
The principal remains untouched by the interest rates.
Because bonds include cash flows linked to interest rates.When interest rates go up, debt (e.g. bond prices) prices fall. Higher interest rates devalue debt, just as lower interest rates increase the value of debt.
If you package those future cash flows as "debt" then you are no longer talking just about the principal.
No, I am not confusing anything.I think you are confusing yourself. The values of all investments are based upon expected future cash flows. Expected cash flow is the basis for all valuations. How else to you value something if not based on future cash flows? You’ve got a little double speak going on here.
You are simply talking cross-purposes.
The value of the debt - if you include future cash flows such as interest - is of course affected by interest.That is not true. The value of debt is affected by 5 things with inflation being one of them. The value of everything is affected by inflation. Inflation is a component of interest rates. Inflation and interest rates are not separate and apart from each other as you imply. They are deeply entwined.
Again, this is not disputed.
But the underlying principal is unaffected by interest rates per se, only in so far as interest rates affect the rate of inflation.
Yes, there is a link between interest rates and inflation within an economy, but it is not interest rates per se that affect the actual value of the principal debt.
Eh?Wrong, it always matters what inflation rates are, because inflation affects the value of everything, not just debt. That’s why inflation rates are so carefully monitored. Inflation rates always change. It’s the nature of the beast. The economy isn’t static. It’s always changing.
Where did I say that it doesn't matter what the rate of inflation is??
Again - you are talking cross-purposes here.While interest is the time value of money, it’s not something magical. There is a rational basis for interest rates which you don’t seem to be able to understand. Interest rates are not divorced from inflation rates as you have asserted. The time value of money must account for expected inflation among other factors like default risk, and it does.
Also I have not said that the interest rates are divorced from inflation - only that inflation and interest are entirely different: i.e. in application, scope etc.
I've skipped some of the rest as the above pretty much covers it.
No, we are simply saying that inflation helps drive down the value of underlying principal of debt.What you and Bilvon are doing is conflating monetary and fiscal policy. The two are not the same. Fiscal policy: how much revenue is raised and how much money is spent is a function of Congress. Monetary policy: the control of money supply is a function of the Federal Reserve, not the POTUS. That too isn’t a red herring. It’s a fact.
It's that simple.
Interest rates don't do it, per se, although they have a relationship to inflation.
It is inflation that does it.
What is it of this that you are struggling with?
Why are you trying to confuse the issue by bringing in interest rates, debt involving future cash flows (e.g. bonds), and the like?
Again, we're talking the underlying principal - please stick to that.This really isn’t that difficult. When interests rates go up for whatever reason, be it inflation or some other demand factor, the value of debt decreases.
Strawman.Your argument boils down to this; you are saying a debt buyer would rather purchase debt yielding 8% when the prevailing market rate is 10%? Good luck with that. I don’t know of any debt investor who would buy debt yielding 8% when they could get 10% for the same risk. Your argument boils down to the greater fool theory of investing.
I have stated above what the argument boils down to.
Please stick to that or feel free to argue in front of a mirror.
I really am not.
Indeed - but we're talking about debt as in the principal.
Not investments.
Not cash flow.
Not anything else.
You have simply confused the matter by introducing bonds et al.
Principal plus future cash flows.
They do not devalue the principal.
That is what was asserted, as that is what was being discussed.
No, you proved that the value of future cash flows changes with the interest rate.
That is not disputed.
The principal remains untouched by the interest rates.
Because bonds include cash flows linked to interest rates.
If you package those future cash flows as "debt" then you are no longer talking just about the principal.
No, I am not confusing anything.
You are simply talking cross-purposes.
The value of the debt - if you include future cash flows such as interest - is of course affected by interest.
Again, this is not disputed.
But the underlying principal is unaffected by interest rates per se, only in so far as interest rates affect the rate of inflation.
Yes, there is a link between interest rates and inflation within an economy, but it is not interest rates per se that affect the actual value of the principal debt.
Eh?
Where did I say that it doesn't matter what the rate of inflation is??
Again - you are talking cross-purposes here.
Also I have not said that the interest rates are divorced from inflation - only that inflation and interest are entirely different: i.e. in application, scope etc.
I've skipped some of the rest as the above pretty much covers it.
No, we are simply saying that inflation helps drive down the value of underlying principal of debt.
It's that simple.
Interest rates don't do it, per se, although they have a relationship to inflation.
It is inflation that does it.
What is it of this that you are struggling with?
Why are you trying to confuse the issue by bringing in interest rates, debt involving future cash flows (e.g. bonds), and the like?
Again, we're talking the underlying principal - please stick to that.
Strawman.
I have stated above what the argument boils down to.
Please stick to that or feel free to argue in front of a mirror.
I really am not.
Truly you are.
Indeed - but we're talking about debt as in the principal.
The principal is irrelevant. You keep getting bogged down in irrelevant detail. You keep getting lost in the forest.
There is a difference between the value of debt and the principal. The two are not the same, and you keep conflating the two.
Not investments.
Not cash flow.
Not anything else.
You have simply confused the matter by introducing bonds et al.
Principal plus future cash flows.
You cannot separate any of those things from an honest discussion of debt. Again, you are confusing “principal” with value. The two are not the same.
Not They do not devalue the principal.
And no one has said otherwise, but the principal isn’t the value of the debt. The actual value of the debt can be more or less than the principal amount.
Not That is what was asserted, as that is what was being discussed.
No, you proved that the value of future cash flows changes with the interest rate.
That is not disputed.
The principal remains untouched by the interest rates.
Because bonds include cash flows linked to interest rates.
If you package those future cash flows as "debt" then you are no longer talking just about the principal.
No, I am not confusing anything.
You are simply talking cross-purposes.
The value of the debt - if you include future cash flows such as interest - is of course affected by interest.
Again, this is not disputed.
But the underlying principal is unaffected by interest rates per se, only in so far as interest rates affect the rate of inflation.
Yes, there is a link between interest rates and inflation within an economy, but it is not interest rates per se that affect the actual value of the principal debt.
Eh?
Where did I say that it doesn't matter what the rate of inflation is??
Again - you are talking cross-purposes here.
Also I have not said that the interest rates are divorced from inflation - only that inflation and interest are entirely different: i.e. in application, scope etc.
I've skipped some of the rest as the above pretty much covers it.
No, we are simply saying that inflation helps drive down the value of underlying principal of debt.
Inflation devalues currency, and since the principal is denominated in currency, it also devalues the principal along with payments associated with the debt. But it doesn’t change the nominal or face value of any debt. If you owned one hundred dollars before, you still own one hundred dollars regardless of inflation or deflation.
But the face value (i.e. notional or theoretical value) is very different from the actual value of the debt. As I previously wrote, when interest rates rise, debt prices (the actual value of the debt) fall. I suggest you read my previous Wells Fargo reference. And interest prices can rise for a number of reasons, and inflation is one of those reasons.
It's that simple.
Interest rates don't do it, per se, although they have a relationship to inflation.
It is inflation that does it.
What is it of this that you are struggling with?
Why are you trying to confuse the issue by bringing in interest rates, debt involving future cash flows (e.g. bonds), and the like?
Again, we're talking the underlying principal - please stick to that.
Strawman.
I have stated above what the argument boils down to.
Please stick to that or feel free to argue in front of a mirror.
You are conflating the value of debt (i.e. price) with the principal or notional value. The two are not the same. Face value or principal is fixed when the debt is created, and it doesn’t change over the life of the debt. Face value is largely irrelevant. However the actual market values of that debt will change over time as interest rates change for similar debts. Increases in inflation, ceteris paribus, decrease the price, i.e. the actual market value of that debt. It also decreases the value or purchasing power of a currency. The face amount of the debt remains fixed regardless. It doesn’t change with inflation or for any other reason. But the purchasing power of the face amount and any related interest payments are also devalued by inflation. Increases in inflation and interest rates will decrease the price of debt, be it a bond or mortgage. A debt is a debt.
There some very different things here a) actual debt value (i.e. price) b) the principal or notional value of the debt, and purchasing power of the currency. In a discussion of inflation, the principal is irrelevant, because it doesn’t change. But that doesn’t mean the value of the debt doesn’t change, because it does. It decreases the market, i.e. price, of debt. Falling interest rates increase the market value of debt. It's just a simple matter of math per my previous Wells Fargo reference.
Inflation doesn't change the notional or principal amount of any debt. However, it does change the purchasing power of the principal amount, and any related interest payments. Whereas inflation will directly affect the market value or price of any debt.
Last edited:
Maybe to the strawman you keep wanting to discuss.The principal is irrelevant.
When you want to actually address what was said, I may actually respond further.
Until then I'll leave you to your mirror.

Why does the federal reserve bank want inflation?
If the fed achieves 2% inflation, the currency loses 1.96% of it's value annually.
Who gains?
Is inflation necessary in support of our economy?
Inflation can also be about psychology, and not just about common sense economics. For example, say we raised the minimum wage to $15/hour for fast food workers. This adds expense to the business that will cause the price of fast food to increase, to balance out the lost revenue of the franchise owner.
The worker will feel more important making $15/hour. However, they may not fully consider the added costs, which at the end of the day, ends up with them buying the same amount, with more money.
With $15/hour, they get to flash a thicker wallet of cash. This is for the crowd, in an entertainment based culture. What they spend is more private and the crowd will not see. The net affect is a gain in social bragging rights even with break even spending.
We all know young men who will spend their whole pay check during a weekend. They do this to flash a larger wallet, with a weeks pay pro-rated to the weekend instead of the entire week. To the ladies, this looks like that have more money. They inflate their wage for the weekend as part of a prestige gam.
There is also the snob appeal angle of inflation psychology. Very few snobs will buy the $2 burger, if they can buy the $10 burger. Even if both were as good, the inflated burger carries more prestige, since it keeps out the riff raft and is more exclusive. These are important to the left, which is why they don;t seem to get economics in terms of the bigger picture.
And what straw man would that be? Please do be specific. The fact is you keep conflating two unrested things and are fixated on something which is totally irrelevant. Contrary to your assertion the value of debt is affected by interest rates.Maybe to the strawman you keep wanting to discuss.
When you want to actually address what was said, I may actually respond further.
Until then I'll leave you to your mirror.
You've been watching Fox News again comrade. There is a psychological component to inflation. After all, economics is a social science. But it has nothing to do with Democrats comrade Wellwisher.Inflation can also be about psychology, and not just about common sense economics. For example, say we raised the minimum wage to $15/hour for fast food workers. This adds expense to the business that will cause the price of fast food to increase, to balance out the lost revenue of the franchise owner.
The worker will feel more important making $15/hour. However, they may not fully consider the added costs, which at the end of the day, ends up with them buying the same amount, with more money.
With $15/hour, they get to flash a thicker wallet of cash. This is for the crowd, in an entertainment based culture. What they spend is more private and the crowd will not see. The net affect is a gain in social bragging rights even with break even spending.
We all know young men who will spend their whole pay check during a weekend. They do this to flash a larger wallet, with a weeks pay pro-rated to the weekend instead of the entire week. To the ladies, this looks like that have more money. They inflate their wage for the weekend as part of a prestige gam.
There is also the snob appeal angle of inflation psychology. Very few snobs will buy the $2 burger, if they can buy the $10 burger. Even if both were as good, the inflated burger carries more prestige, since it keeps out the riff raft and is more exclusive. These are important to the left, which is why they don;t seem to get economics in terms of the bigger picture.
Contrary to your assertion the value of debt is affected by interest rates.
This is the pain point for Baldee.
Are you referring to influence of interest rate on currency or foreign exchange, if so then principle debt may be affected by interest rates?
Indeed it is.This is the pain point for Baldee.
Are you referring to influence of interest rate on currency or foreign exchange, if so then principle debt may be affected by interest rates?
No, that's a different subject. This is limited to the effect on interest rates on the value of debt. Interest rates also affect the value of currencies. But the value of currencies is a separate discussion and that one of the places where Baldee gets confused.
The principal isn't affected by anything. It's fixed at the time of purchase and it doesn't change. The principal amount is always the same. Today a debt may trade a par, tomorrow it may not. The value of the currency (i.e. purchasing power) may change over time. But the value of the debt, independent of currency valuations, will change as interest rates change.